
Price, loans & investment · · 4 min read · By Sorrel Buildcon
EMI for 40 Lakh Home Loan: Rate, Tenure and Total Interest Explained
Quick answer
The EMI for 40 lakh home loan at an illustrative 8.5% p.a. is about ₹34,713 for 20 years, ₹39,390 for 15 years and ₹32,209 for 25 years. Over 20 years you would repay about ₹83.3 lakh, of which about ₹43.3 lakh is interest. A ₹40 lakh loan typically funds a home of about ₹50 lakh with 20% down.
How the EMI for 40 lakh home loan is calculated
An EMI (equated monthly instalment) repays interest and principal together. The standard formula is EMI = P × r × (1 + r)n ÷ ((1 + r)n − 1), where P is the loan amount, r is the monthly interest rate (annual rate ÷ 12 ÷ 100) and n is the number of months. For a ₹40 lakh loan at 8.5% for 20 years, r is about 0.00708 and n is 240, giving an EMI of about ₹34,713. All figures in this post are illustrative; your bank's rate and terms decide the actual amount.
EMI for 40 lakh home loan by interest rate (20-year tenure)
| Rate p.a. | Approx. EMI on ₹40 lakh |
|---|---|
| 7.5% | ₹32,224 |
| 8.0% | ₹33,458 |
| 8.5% | ₹34,713 |
| 9.0% | ₹35,989 |
| 9.5% | ₹37,285 |
| 10.0% | ₹38,601 |
Each 0.5% change in rate moves the EMI by roughly ₹1,250–1,300 a month. A good credit score can help you get a lower rate — see CIBIL score for a home loan.
EMI and total interest by tenure (8.5%)
| Tenure | EMI / total paid / total interest |
|---|---|
| 10 years | ₹49,594 / ₹59.5 lakh / ₹19.5 lakh |
| 15 years | ₹39,390 / ₹70.9 lakh / ₹30.9 lakh |
| 20 years | ₹34,713 / ₹83.3 lakh / ₹43.3 lakh |
| 25 years | ₹32,209 / ₹96.6 lakh / ₹56.6 lakh |
| 30 years | ₹30,757 / ₹110.7 lakh / ₹70.7 lakh |
Stretching from 20 to 30 years lowers the EMI by only about ₹4,000 but adds about ₹27 lakh of interest. A longer tenure is useful for eligibility, but plan to prepay.
Why early EMIs are mostly interest
In the first year of a 20-year ₹40 lakh loan at 8.5%, you pay about ₹4.17 lakh in EMIs, but only about ₹80,000 of that reduces the principal; roughly ₹3.37 lakh is interest. The balance shifts towards principal slowly over the years. This is why prepayments made early have the biggest effect.
The power of small prepayments
Illustrative example: on a ₹40 lakh loan at 8.5% for 20 years, prepaying just ₹1 lakh at the end of every year (keeping the EMI unchanged) clears the loan in about 13 years instead of 20 and cuts total interest from about ₹43.3 lakh to about ₹26.4 lakh — a saving of roughly ₹17 lakh. Most banks do not charge prepayment penalties on floating-rate home loans to individuals; confirm with your lender. See fixed vs floating rates.
Salary needed for a ₹40 lakh loan
Lenders usually want your total EMIs within about 40–50% of net monthly income, depending on income level and the bank's policy. For an EMI of about ₹34,713, a net monthly income of roughly ₹70,000–85,000 is a practical range, lower if a co-applicant adds income. Existing car or personal loan EMIs reduce eligibility. Read home loan eligibility basics and home loan documents checklist.
Tax benefits (old regime)
For a self-occupied home, the old tax regime allows a deduction of up to ₹1.5 lakh a year on principal under Section 80C and up to ₹2 lakh a year on interest under Section 24(b). In the early years of a ₹40 lakh loan, interest alone is above ₹3 lakh, so the 24(b) limit is usually fully used. Rules can change and differ under the new regime — check current rules with a tax advisor.
What a ₹40 lakh loan can buy
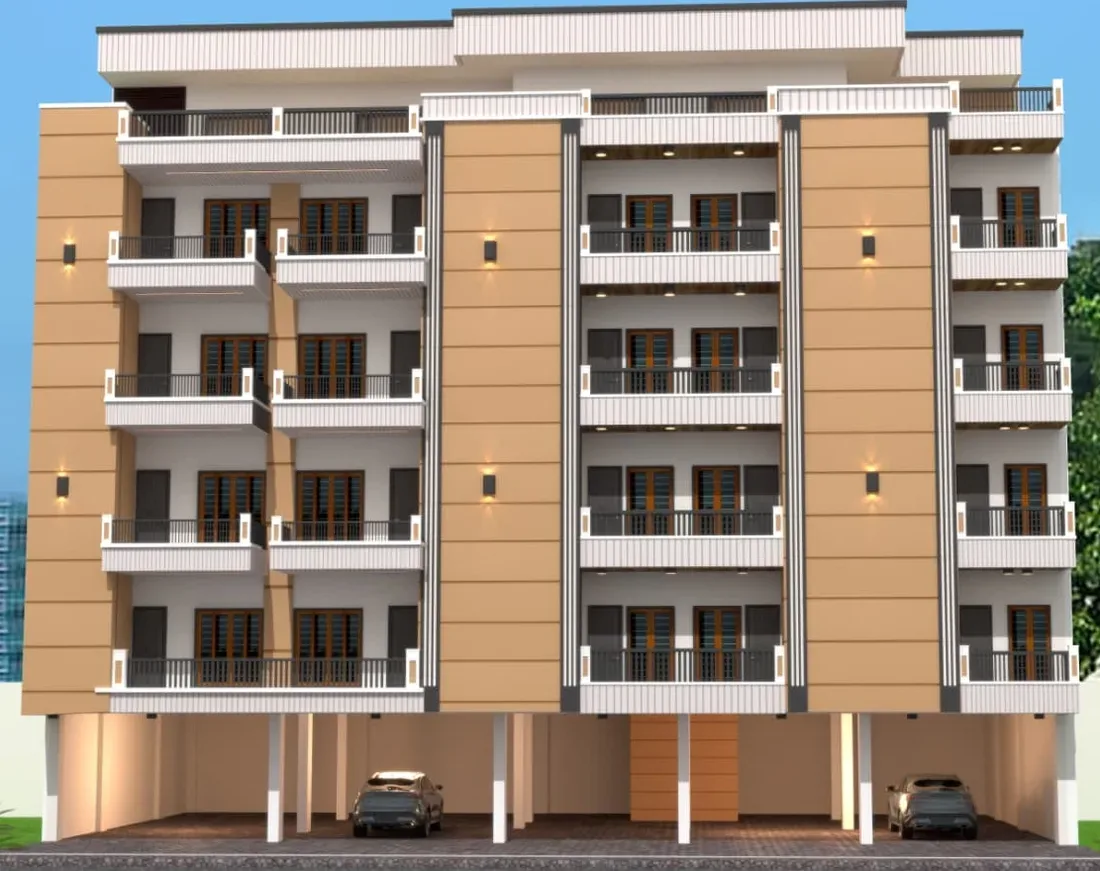
With 80% financing, a ₹40 lakh loan supports a home of about ₹50 lakh. At Sorrel Heights, Greater Noida West, the 2BHK + Study (1280 sq.ft super area, two toilets) is priced at approximately under ₹50 lakh all-inclusive, as shared by Sorrel Buildcon; prices are indicative and revised from time to time, so check the current price list & payment plan sheet. GST at 1% is extra, and stamp duty and registration are paid at offer of possession. Under-construction homes are paid in stages, so you may pay pre-EMI interest before full EMIs begin — see pre-EMI vs full EMI and the Sorrel buying process.
Plan your purchase
Use these tables to set your EMI comfort zone, then see the 2BHK + Study flats in Jalpura layout, get the current price list & payment plan sheet and book a visit through contact the Sorrel team.
Facts about Sorrel Heights on this page come from the official brochure and Sorrel Buildcon. General guidance is for information only — confirm rules and rates with the relevant authority before you act.