
Buyer situations · · 6 min read · By Sorrel Buildcon
Buying a Home as a Woman in Uttar Pradesh
Quick answer
Buying a home as a woman in Uttar Pradesh has two real advantages: the state gives a stamp duty concession where a woman is the buyer, and several lenders price home loans for women borrowers a little lower. Rates and conditions change, so confirm the current rate with the sub-registrar or on IGRS before you budget, and compare at least three lenders.
Why buying a home as a woman in UP is worth planning carefully
Two women in the same office, buying identical flats in the same building, can end up paying different amounts at registration and different EMIs for twenty years — purely because one of them planned the paperwork and the other did not. The concessions available to women buyers in Uttar Pradesh are real, but they are rule-bound: they depend on who is named on the sale deed, in what share, and on the value of the property.
This guide sets out what to check, in what order, and where to verify it yourself rather than trusting a WhatsApp forward. Nothing here replaces the sub-registrar's office or your lender — both can confirm the current position in one visit or one call.
The stamp duty concession: what to verify, not assume
Uttar Pradesh has long offered a concession on stamp duty where the buyer is a woman, usually as a reduction on the applicable rate up to a stated property value, with the normal rate applying above that ceiling. Both the rate and the ceiling have been revised over the years, and separate registration charges apply on top.
So treat the concession as a question, not a number. Check the current rate, the value limit and the conditions with the sub-registrar's office for your tehsil, or on the IGRS Uttar Pradesh portal, before you finalise the registration amount. Ask specifically how it applies when a woman is a joint owner rather than the sole owner, and what share must be in her name. Our post on stamp duty and registration charges explains how the total is calculated from circle rate and consideration value.
Sole ownership or joint — how to decide
| Sole ownership (woman buyer) | Cleanest route to the women's stamp duty concession. Loan eligibility rests on one income. Full control over sale, will and nomination. |
|---|---|
| Joint with spouse | Two incomes raise loan eligibility. Both co-owners can claim tax deductions in proportion to their share and repayment. Concession treatment depends on the share registered in the woman's name — confirm locally. |
| Joint with a parent or sibling | Useful where one person has the income and the other the savings. Put the contribution and share in writing before registration. |
| Woman as co-applicant but not co-owner | Common with lenders, but she gets no tax benefit and no ownership. Avoid unless there is a reason. |
Read the benefits of joint ownership before you sign anything, because changing names after registration means a fresh deed and fresh stamp duty.
Home loans: where women borrowers can gain
Several banks and housing finance companies advertise a small rate concession for women borrowers, typically a few basis points, applicable when the woman is the primary applicant or a co-owner. A few basis points sound trivial and are not: on a ₹50 lakh loan over 20 years, a 0.05% lower rate saves roughly ₹30,000 in interest, and negotiating 0.25% saves well over a lakh.
Do the comparison properly. Ask each lender for the rate, the processing fee, whether the rate is linked to an external benchmark, and the prepayment terms on a floating-rate loan. Check the current repo-linked position published by the Reserve Bank of India, and read home loan eligibility basics and the home loan documents checklist before you apply.
Documents to keep ready in your own name
- Identity and address: PAN, Aadhaar, and one more photo ID.
- Income: three to six months of salary slips and two to three years of ITRs, or business proof if self-employed.
- Banking: six to twelve months of statements for the account your salary or business income enters.
- Own contribution: proof of the source of your down payment — savings, a sold asset, a gift deed from a parent.
- Property papers: booking letter, allotment, payment receipts and the builder's documents.
A frequent obstacle is money that sits in a parent's or spouse's account. If a family member is funding part of the purchase, transfer it into your account with a clear gift letter well before you apply, so the trail is simple to explain.
Safety features that matter in daily life
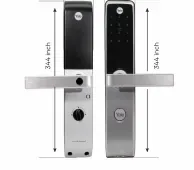
For women living alone or returning late, security is not an amenity line — it changes whether a home feels usable. The Sorrel Heights specification list includes a smart lock on the front door, so there is no key to hand over to a landlord, a plumber or a courier, and a 24×7 smart motion-detection camera covering the approach. Sensor lights in the toilets help at night, and a lift to all floors in a low-rise with only five homes per floor means you pass the same few neighbours rather than a crowded lobby of strangers.
Look beyond the flat too: gate manning at night, lighting on the internal roads, whether the parking is overlooked, and how far the nearest autos or cabs reliably come. See Sorrel Heights specifications and our guide to the smart lock.
Which home, and what it costs at Sorrel Heights
A single professional or a couple starting out often finds the 2BHK + Study (1280 sq.ft, 2 toilets) the right size — the study takes the desk out of the bedroom, and the approximate all-inclusive price is under ₹50 lakh. Families needing a third room look at the 3BHK homes at 1700–1750 sq.ft, approximately ₹60–70 lakh all-inclusive. All prices are indicative, shared by Sorrel Buildcon and revised from time to time; ask for the current sheet on price list & payment plan.
Remember what sits on top of the base price: PLC and meter charges, 1% GST on an under-construction home, and stamp duty plus registration payable at the offer of possession — which is exactly where the women's concession applies. Read the total cost of buying a flat so nothing arrives as a surprise.
A sensible order of steps
- Fix your budget from your own EMI capacity, not from the maximum loan offered.
- Get a pre-approval so you negotiate as a ready buyer — see pre-approval benefits.
- Shortlist projects and visit; check the project's registration on the UP RERA portal portal.
- Decide ownership structure and shares in writing before booking.
- Confirm the current stamp duty rate for women buyers with the sub-registrar or IGRS.
- Register, then update nomination on the loan, insurance and utilities.
Take the next step
The best use of an afternoon is a site visit with your questions written down. View the unit drawings on Sorrel Heights floor plans, request the current indicative price sheet on price list & payment plan, and book a visit through contact the Sorrel team. Sorrel Buildcon sells direct from its Greater Noida West office, so you can ask about ownership, payment stages and registration in one conversation.
Documents in your name
If you are the sole or primary owner, make sure the allotment letter, agreement and receipts are in your name, and that payments come from your account or are clearly recorded.
Building your credit
A home loan in your name builds your credit history. Pay on time and keep records — it helps with future financial goals.
Security checklist
- Smart lock with your own code
- Building camera coverage at entry and parking
- Lift access to your floor
- Neighbours you can call
Facts about Sorrel Heights on this page come from the official brochure and Sorrel Buildcon. General guidance is for information only — confirm rules and rates with the relevant authority before you act.