
Price, loans & investment · · 7 min read · By Sorrel Buildcon
Special BSP & Payment Plans — Explained
Quick answer
A payment plan decides when you pay; a special BSP plan changes the base selling price itself depending on that timing. Plans that collect more money earlier usually carry a lower BSP, and plans that spread payments carry a higher one. Compare the final total cost including GST and your own cash flow, not the headline rate alone.
What a special BSP plan actually is
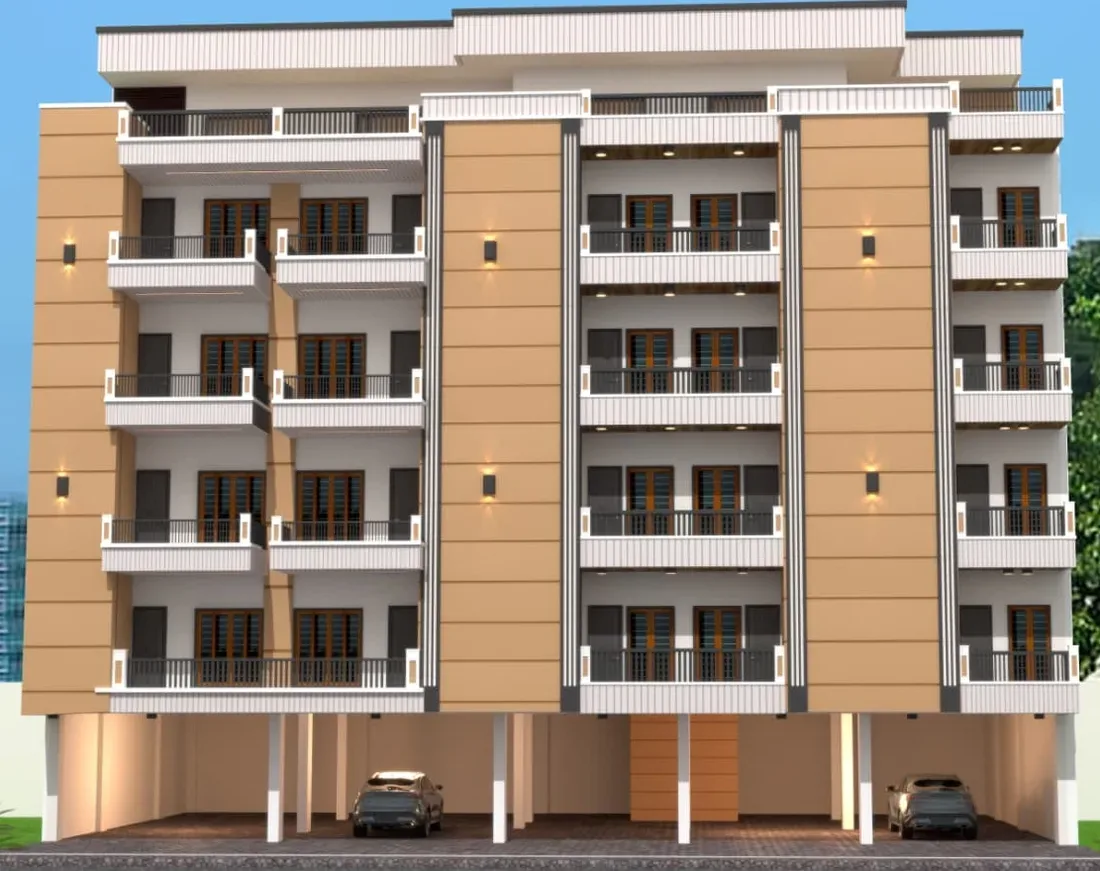
BSP stands for basic sale price — the core price of the home before preferential location charges, meter and utility charges, taxes and registration. A special BSP plan is simply an offer in which the builder quotes a different basic sale price depending on how and when you pay. Pay a larger share upfront and the BSP is typically lower; spread payments across construction milestones and the BSP is typically higher. Nothing about the home changes — the same 1280 sq.ft 2BHK + Study or 1700 sq.ft 3BHK, the same specification, the same lift and the same terrace on a duplex. Only the price and the schedule move.
Sorrel Buildcon offers special BSP plans for Sorrel Heights depending on payment timing, and the plans open at any given moment change, as does the price sheet itself. Whatever you read on any website, the only binding numbers are the ones on the current cost sheet and in your agreement — ask for them on price list & payment plan. For how BSP sits alongside PLC and super area in the first place, read BSP, PLC and super area explained.
The three plan families
| Plan type | How you pay | Typical trade-off |
|---|---|---|
| Down-payment plan | A large share soon after booking, balance at possession | Usually the lowest BSP; needs the most cash or the earliest loan disbursement |
| Construction-linked plan | Instalments tied to slab and finishing milestones | Payments follow visible progress; usually a higher BSP than a down-payment plan |
| Time-linked plan | Fixed amounts on fixed calendar dates | Easy to budget, but dates do not move if construction slows |
| Possession-linked plan | Smaller share now, large share at possession | Lowest early outgo; usually the highest BSP |
| Subvention-style plan | Builder or lender bears interest for a defined period | Read the terms closely — the cost is usually inside the price |
Not every builder offers every family, and terms differ project by project. Ask which plans are currently open for Sorrel Heights rather than assuming a plan you read about elsewhere applies.
Why earlier money buys a lower price
The logic is plain. Construction needs funding, and a builder can fund it either from buyers or from a lender. Money from buyers arriving early reduces the interest the project pays, and part of that saving can be passed back as a lower basic sale price. That is the whole economics of a special BSP plan. It is also why the discount is usually larger for a down-payment plan than for a construction-linked one.
The mirror image matters just as much. When you pay early for an under-construction home, you take on more risk: your money is in the project sooner, and it is not earning anything for you in the meantime. That is a real cost even when it does not appear on the cost sheet. A useful test before you choose the cheapest plan is simply this — if the money were not in this home, what would it be doing, and can the household manage without it for the next two to three years? Under construction vs ready to move sets out the wider trade-off.
An illustrative comparison
The numbers below are hypothetical, chosen for easy arithmetic, and are not a Sorrel Heights quotation. Assume a base price of ₹50 lakh under a construction-linked plan, and assume a down-payment plan offers a BSP 3% lower. The actual difference, if any, is on the current cost sheet.
- Construction-linked BSP: ₹50,00,000. Down-payment BSP at 3% lower: ₹48,50,000. Saving on BSP: ₹1,50,000.
- GST at 1% applies on the price, so the tax also falls slightly — ₹50,000 becomes ₹48,500, a further ₹1,500.
- Against that, you fund roughly ₹35–40 lakh two to three years earlier than you otherwise would.
So the question is never "which BSP is lower". It is "is the saving worth funding the home earlier". For a buyer sitting on maturing deposits or a sale proceed, the answer is often yes. For a buyer whose down payment is still being saved month by month, a construction-linked plan is usually the sane choice even at a higher price. Work out your own monthly capacity first with home loan eligibility basics.
How to compare two cost sheets properly
- Ask for both sheets in writing, on the same date, for the same unit number.
- Compare the bottom line, not the rate: BSP plus PLC plus meter and utility charges, then GST at 1% on top.
- Check what is excluded. Stamp duty and registration are payable at the offer of possession and are not part of the price.
- Line up the dates. Write each instalment against the month you would actually pay it, then against the month your savings or loan disbursement arrives.
- Check the interest clause for delayed payment, and the rate at which it is charged.
- Check the cancellation and transfer terms. A plan that has taken 40% of the price from you early is a plan you cannot walk away from cheaply.
- Confirm the plan in the agreement, not only in a brochure or a WhatsApp message.
The total cost of buying a flat lists every line item so nothing surprises you at the end, and GST on under-construction flats explains why the tax is 1% in the affordable category and 5% otherwise.
Matching the plan to your home loan
Your payment plan and your loan disbursement have to agree, because a bank releases money against demand letters, not in advance. Three things follow.
First, a down-payment plan usually needs a large single disbursement soon after the agreement, so the loan must be sanctioned and the property legally cleared before you commit to that plan. Second, on an under-construction home the bank disburses in stages, and on the amount released you either pay only interest (pre-EMI) or start a full EMI on the disbursed portion. Pre-EMI keeps the early outgo low but stretches total interest, so ask the lender to show both. Third, if you are still paying rent while the home is built, the rent plus pre-EMI together are what your household actually feels each month — budget on that combined figure, not the EMI alone.
Get the bank's disbursement policy in writing at sanction stage, and keep the documents checklist ready so a demand letter never waits on paperwork.
Questions worth asking before you sign
- Which special BSP plans are open for this unit today, and until when?
- Is the quoted amount all-inclusive of PLC and meter charges, or are those added later?
- What is the GST rate applied, and on which components?
- What is payable at the offer of possession besides stamp duty and registration?
- What happens if I miss an instalment by a fortnight?
- Can I switch plans after booking, and at what cost?
- Is the payment schedule reproduced in the agreement for sale?
Read the agreement for sale clauses to read and questions to ask a builder before booking before the meeting, and verify the project independently using how to verify a UP RERA project and UP RERA portal. Sorrel Buildcon sells direct, without a middleman, so the person quoting the plan is the person who can confirm it.
Ask for today's plans and cost sheet
A special BSP plan is only meaningful against a live price sheet, because both the plans and the prices are revised from time to time. Indicative all-inclusive pricing at Sorrel Heights, Novelty Green, Jalpura, Greater Noida West, is under ₹50 lakh for the 2BHK + Study, ₹60–70 lakh for the 3BHK homes and under ₹1 crore for the duplexes — approximate, shared by Sorrel Buildcon and revised from time to time.
Request the current sheet on price list & payment plan, see how booking works in the buying process, read how to book a flat at Sorrel Heights, check the company record on customer trust factors, compare the floor plans, and book a site visit so you can discuss plans and cash flow with the team in person.
Cash flow matters
A plan that saves money on paper is only good if you can pay on time. Missing a payment can attract interest — 18% per year under the Sorrel Heights terms — which quickly cancels any discount. Map every payment to a source: savings, loan disbursement or sale of another asset.
Loans and payment plans
Banks disburse in stages for under-construction homes. If a plan asks for large early payments, check how much your bank will release at that stage and how much must come from your savings.
Ask for it in writing
Whatever plan you choose, get the schedule, BSP and total cost in writing before you sign the application form. See buying process.
Facts about Sorrel Heights on this page come from the official brochure and Sorrel Buildcon. General guidance is for information only — confirm rules and rates with the relevant authority before you act.