
Buyer situations · · 6 min read · By Sorrel Buildcon
NRI Buying a Flat in Greater Noida West — A Practical Guide
Quick answer
An NRI buying a flat in Greater Noida West can generally purchase residential property under FEMA rules, paying by inward remittance or from an NRE, NRO or FCNR account. Most banks offer NRI home loans repaid in rupees, and a registered power of attorney lets a relative complete registration. Confirm the current position with your bank and a chartered accountant before you remit money.
Can an NRI buy residential property in India?
Under the Foreign Exchange Management Act framework, a person of Indian origin living abroad is generally permitted to buy residential and commercial immovable property in India without any special approval. The well-known restriction is on agricultural land, plantation property and farmhouses, which generally cannot be purchased, though they may be inherited.
Two practical cautions. First, rules for an NRI, an OCI cardholder and a foreign national of non-Indian origin are not identical, so establish which category you fall in. Second, these rules are updated from time to time. Nothing in this guide is a substitute for confirmation — check the current position with your bank, which will refer to the applicable Reserve Bank of India directions, and with a chartered accountant who handles NRI files.
How the money must move
This is where most NRI purchases go wrong, and the fix is simple: keep every rupee traceable through banking channels.
- Inward remittance from your overseas bank to the seller or builder, through normal banking channels.
- NRE account — funds you brought from abroad; freely repatriable, subject to conditions.
- NRO account — rupee income earned in India such as rent or dividends; repatriation is subject to limits and documentation.
- FCNR deposit — foreign currency deposits held in India.
What you should not do is pay in foreign currency cash, or route money through a friend's resident account for convenience. Keep the foreign inward remittance advice, bank statements and every receipt filed together — you will need them years later if you ever sell and repatriate. Read documents needed to buy a flat in Uttar Pradesh for the property-side paperwork.
NRI home loans, in outline
Most large Indian banks and housing finance companies lend to NRIs for residential purchase. What tends to differ from a resident loan:
| Currency | Loan is sanctioned and repaid in Indian rupees |
|---|---|
| Repayment source | EMIs from your NRE or NRO account, or by inward remittance |
| Income documents | Overseas salary slips, employment contract, overseas bank statements, tax returns of the country of residence |
| Identity documents | Passport, visa or residence permit, overseas address proof, PAN |
| Tenure | Often shorter than for resident borrowers |
| Co-applicant | Many banks prefer a resident Indian co-applicant or POA holder |
Rates, tenure and loan-to-value differ between lenders and change frequently, so collect two or three written sanction terms rather than one. Our home loan eligibility basics post explains how lenders assess income and EMI capacity.
Power of attorney: doing it properly
Very few NRIs can fly in for every signature. A power of attorney lets a trusted person — usually a parent, sibling or spouse resident in India — sign the agreement, complete registration and take possession on your behalf.
- Draft it narrowly. Name the specific property, the specific acts permitted, and a validity period. A vague general POA is dangerous.
- Execute it abroad before the Indian consulate, or before a notary and then get it apostilled or attested as required in your country of residence.
- Get it adjudicated or stamped in India as the state requires before it is used for registration in Uttar Pradesh.
- Choose the holder carefully. A POA is real authority, not a formality.
- Keep the original safe and give certified copies where copies suffice.
Your lawyer and the sub-registrar's office in Gautam Buddha Nagar will confirm exact requirements; see IGRS Uttar Pradesh for the state registration portal.
Tax points to raise with your CA
Treat this section as a list of questions, not as advice. Tax positions for NRIs turn on residential status, treaty benefits and the year of transaction.
- TDS on purchase. Buyers in India commonly have to deduct tax at source on property purchases above a threshold value. Confirm the rate and procedure applicable to your transaction and who files it.
- Rental income from the property is taxable in India, with TDS obligations on the tenant in many cases.
- Home loan deductions. Under the old regime, Section 80C allows principal repayment up to ₹1.5 lakh and Section 24(b) allows interest up to ₹2 lakh for a self-occupied home — availability depends on your Indian income and chosen regime. Check current rules with a tax advisor.
- Capital gains on a future sale, and TDS the buyer must deduct when the seller is an NRI.
- Repatriation limits on sale proceeds from an NRO account, and the certificates your bank will want.
Also read stamp duty and registration charges, since those are payable in India regardless of where you live.
Buying remotely without losing control
The risk in a remote purchase is not fraud so much as drift — small decisions made without you. Build a routine instead:
- Ask for a live video walkthrough of the actual floor and unit, not a recorded render.
- Ask for the price sheet, the specification page and the draft agreement by email, and read them in full.
- Fix a recurring call slot with the sales team and the same point of contact each time.
- Have a trusted person in India visit at least twice — once early, once close to handover.
- Photograph and date everything at handover, and prepare a snag list before you accept the keys. Use the snag list guide and possession handover checklist.
Buying from a developer that sells directly helps here, because there is one accountable contact rather than a chain of intermediaries.
Why Greater Noida West suits many NRI buyers
Two reasons come up repeatedly. The first is size: at the same budget, homes here are larger than in older Noida sectors, which matters when parents will occupy the flat or when you need space for visits home. The second is family proximity — many NRI buyers are buying near relatives already living in the NCR.
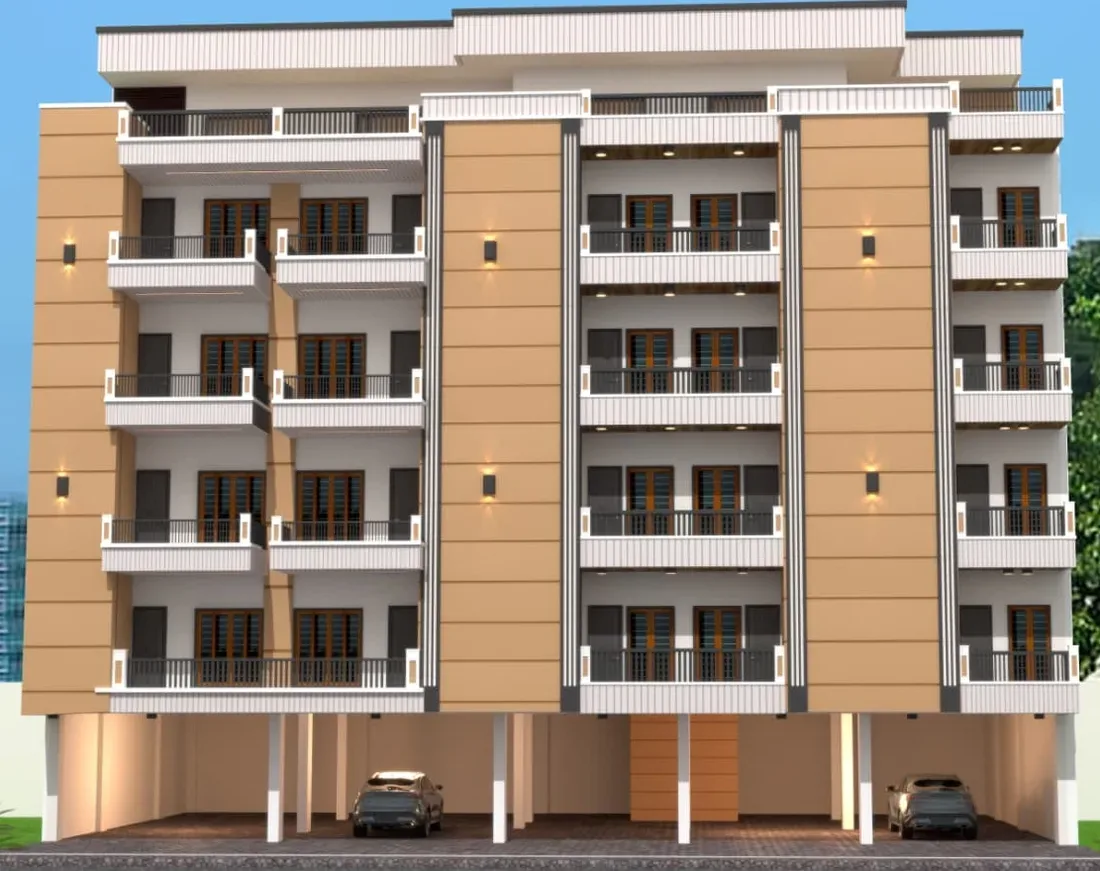
Sorrel Heights, in Jalpura, Greater Noida West, is a low-rise project with a lift to all floors and five homes on a typical floor. Homes run from a 1280 sq.ft 2BHK + Study through 1700 and 1750 sq.ft 3BHK variants to duplexes of up to 2650 sq.ft with open terraces. If parents will live there, read elder-friendly home design before choosing a floor, and see the neighbourhood on Sorrel Heights location.
Confirm the rules, then take the next step
Sequence matters: speak to your bank and your CA first, get the FEMA and tax position for your exact status in writing, and only then commit money. On the property side, request the current price list & payment plan sheet, study the Sorrel Heights floor plans, read the paperwork sequence under buying process, and set up a video walkthrough or a family visit through contact the Sorrel team.
Tax points to discuss with an adviser
- TDS on property purchase and later sale
- Tax on rental income in India
- Repatriation limits and documentation
- Double taxation relief in your country of residence
Rules change; get advice specific to your situation.
Visiting efficiently
If you are in India for a short trip, book site visits, bank meetings and document signing back-to-back. Ask the builder to send documents in advance so you can read them before arriving.
Managing the home from abroad
Appoint a trusted local contact for possession, handover inspection and utilities. A smart lock makes it easy to give temporary access to family or a property manager.
Facts about Sorrel Heights on this page come from the official brochure and Sorrel Buildcon. General guidance is for information only — confirm rules and rates with the relevant authority before you act.